What Actually Appears on Your Credit Report?

August 18, 2026

A credit report is a detailed record of how you have managed certain types of credit and debt. Lenders, landlords, insurers, and other organizations may use information from your credit report when making decisions about applications, rates, deposits, or other financial matters.


Understanding what appears on your credit report can make it easier to monitor your financial history, identify errors, and build stronger credit habits. Portside Finance encourages consumers to review their credit information regularly and understand how everyday borrowing and payment decisions may affect their financial profile.
Credit history report showing the personal identification information section

Personal Identification Information

Your credit report typically includes identifying information used to match the report to you.


This may include your name, current and previous addresses, date of birth, Social Security number information, and sometimes current or former employers.


This section does not generally affect your credit score. Its purpose is primarily identification.


Because information can come from multiple creditors and applications, you may notice old addresses or variations of your name. However, unfamiliar information can be worth investigating, particularly if it may indicate that someone else’s information has been mixed with yours.
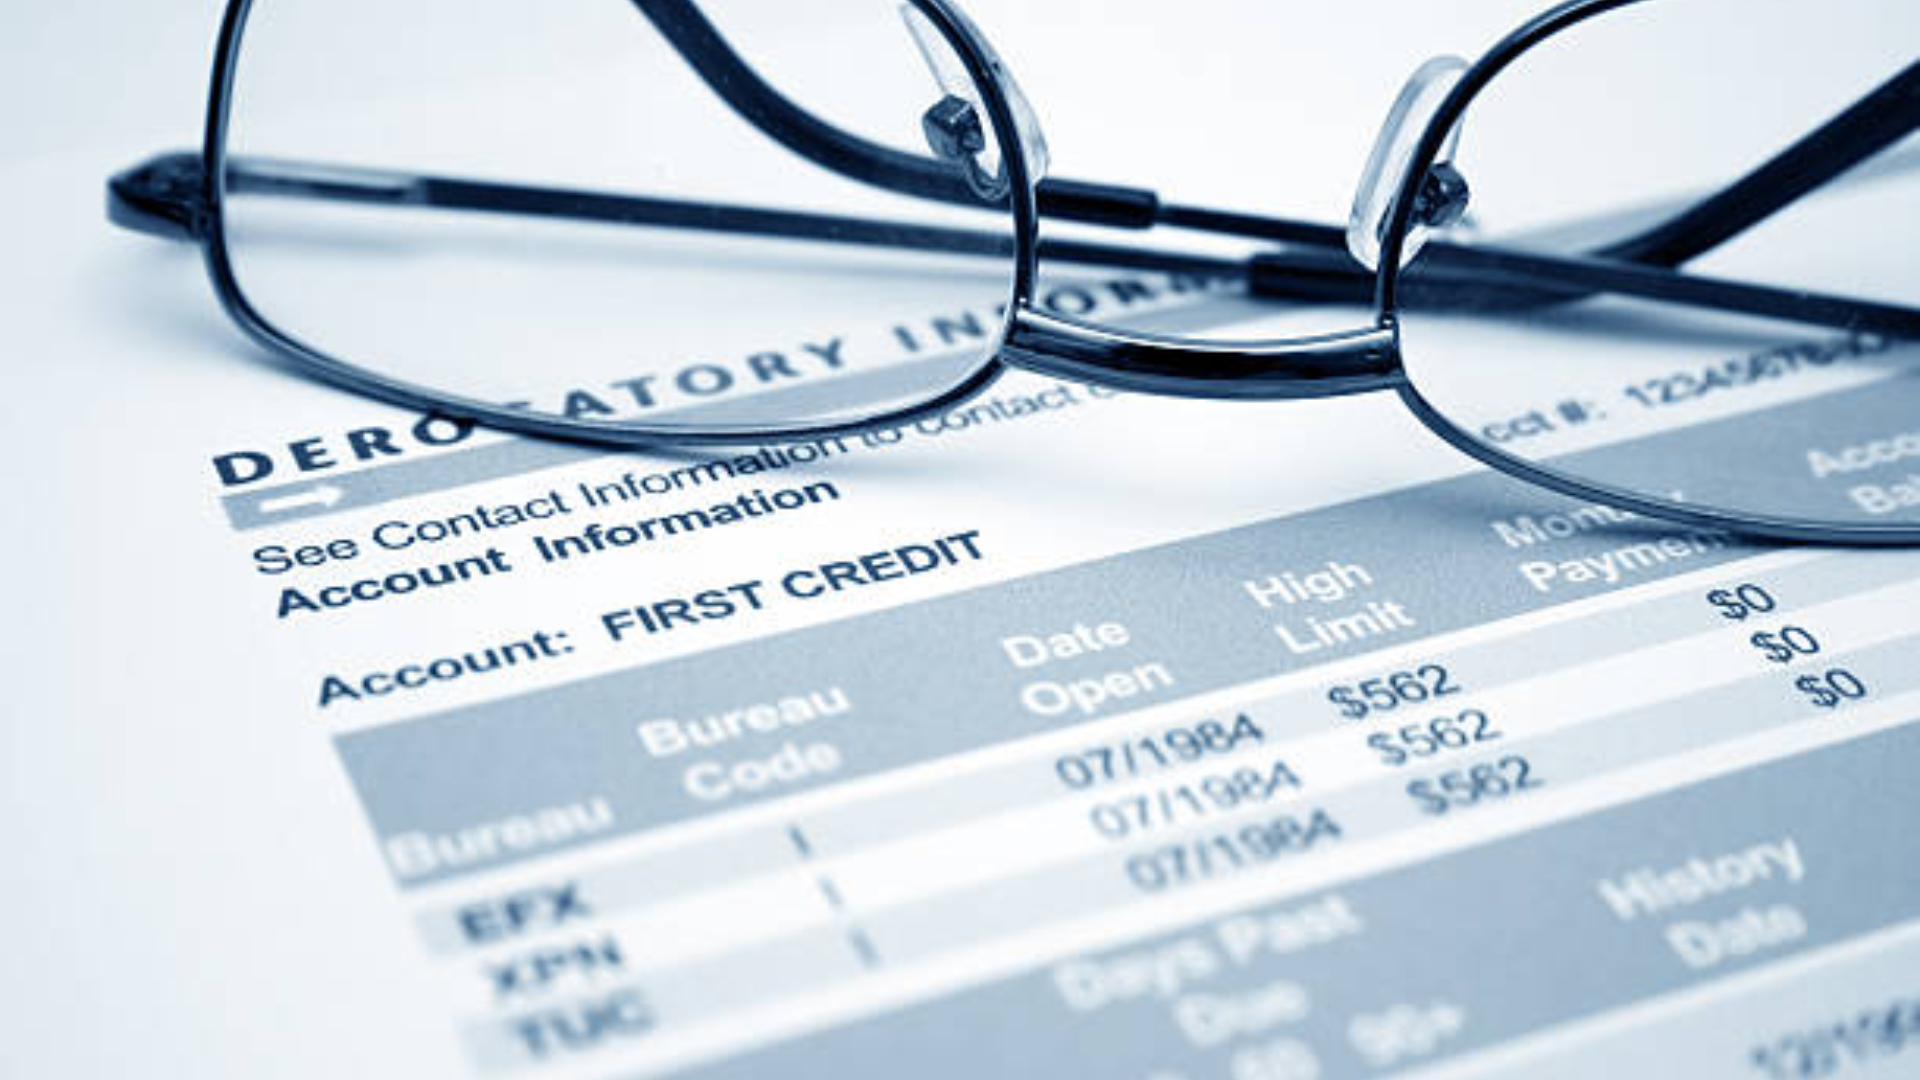
credit report showing credit accounts

Your Credit Accounts

A major portion of your credit report consists of accounts reported by lenders and creditors.


These may include:

  • Credit cards
  • Auto loans
  • Mortgages
  • Student loans
  • Personal loans
  • Other installment accounts


For each account, the report may show when it was opened, the current balance, credit limit or original loan amount, payment status, and account history.


Open accounts can remain on the report as long as they are active and reported. Closed accounts may also remain for a period of time, depending on their status and the applicable reporting rules.
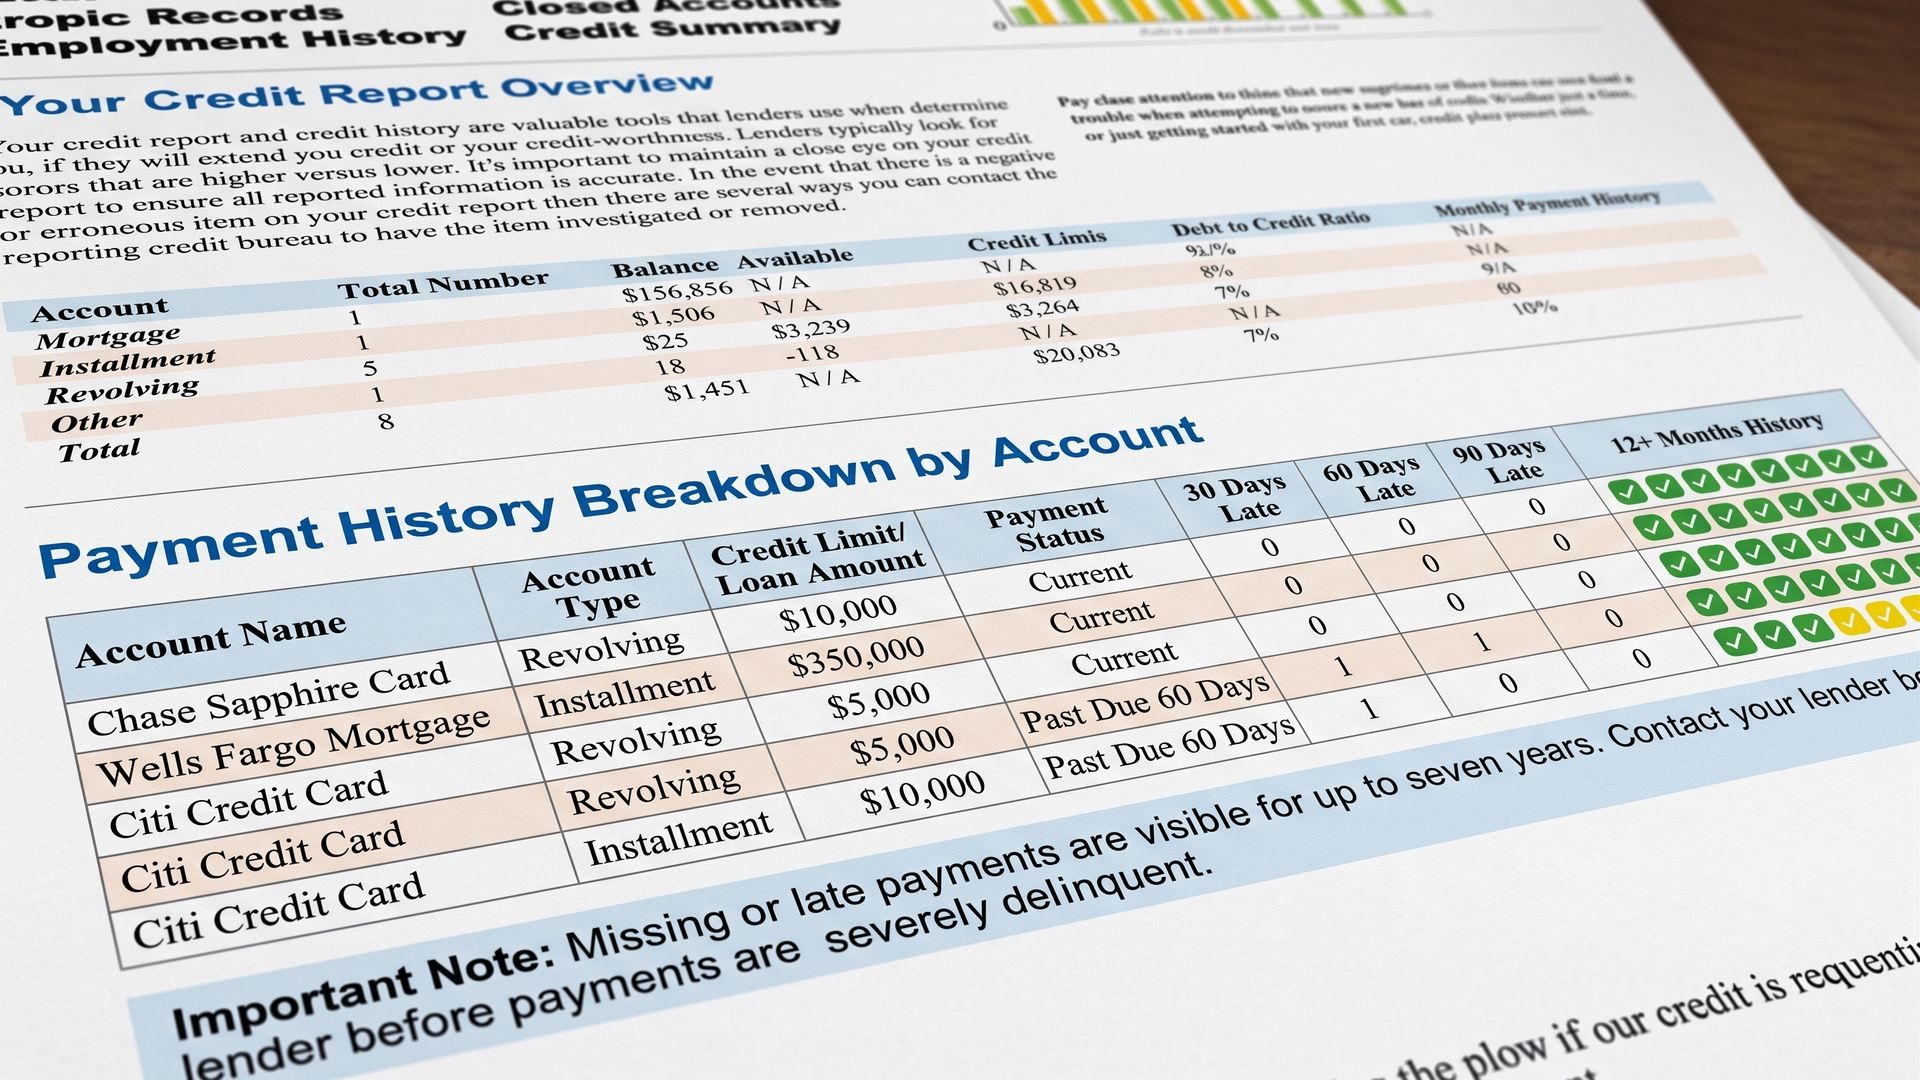
credit report showing the payment history

Payment History

Payment history is one of the most important parts of a credit report.


Creditors may report whether payments were made on time or became 30, 60, 90, or more days past due. Late payments can remain visible for years, which is one reason paying bills on time is such an important financial habit.


If you are struggling to make a payment, contacting the lender before the account becomes seriously delinquent may provide more options than ignoring the problem.


Keeping a calendar of due dates or using automatic payments can also help reduce the risk of missed payments.
a lender checking the credit report for a credit inquiry

Credit Inquiries

Credit reports may also show who has requested access to your credit information.


A hard inquiry generally occurs when you apply for new credit and authorize a lender to review your report. These inquiries can sometimes have a small, temporary effect on a credit score.


Soft inquiries may occur when you check your own credit, receive a prequalification offer, or when an existing creditor reviews your account. These typically do not affect your credit score.


Reviewing your inquiries can also help you recognize applications you do not remember making.
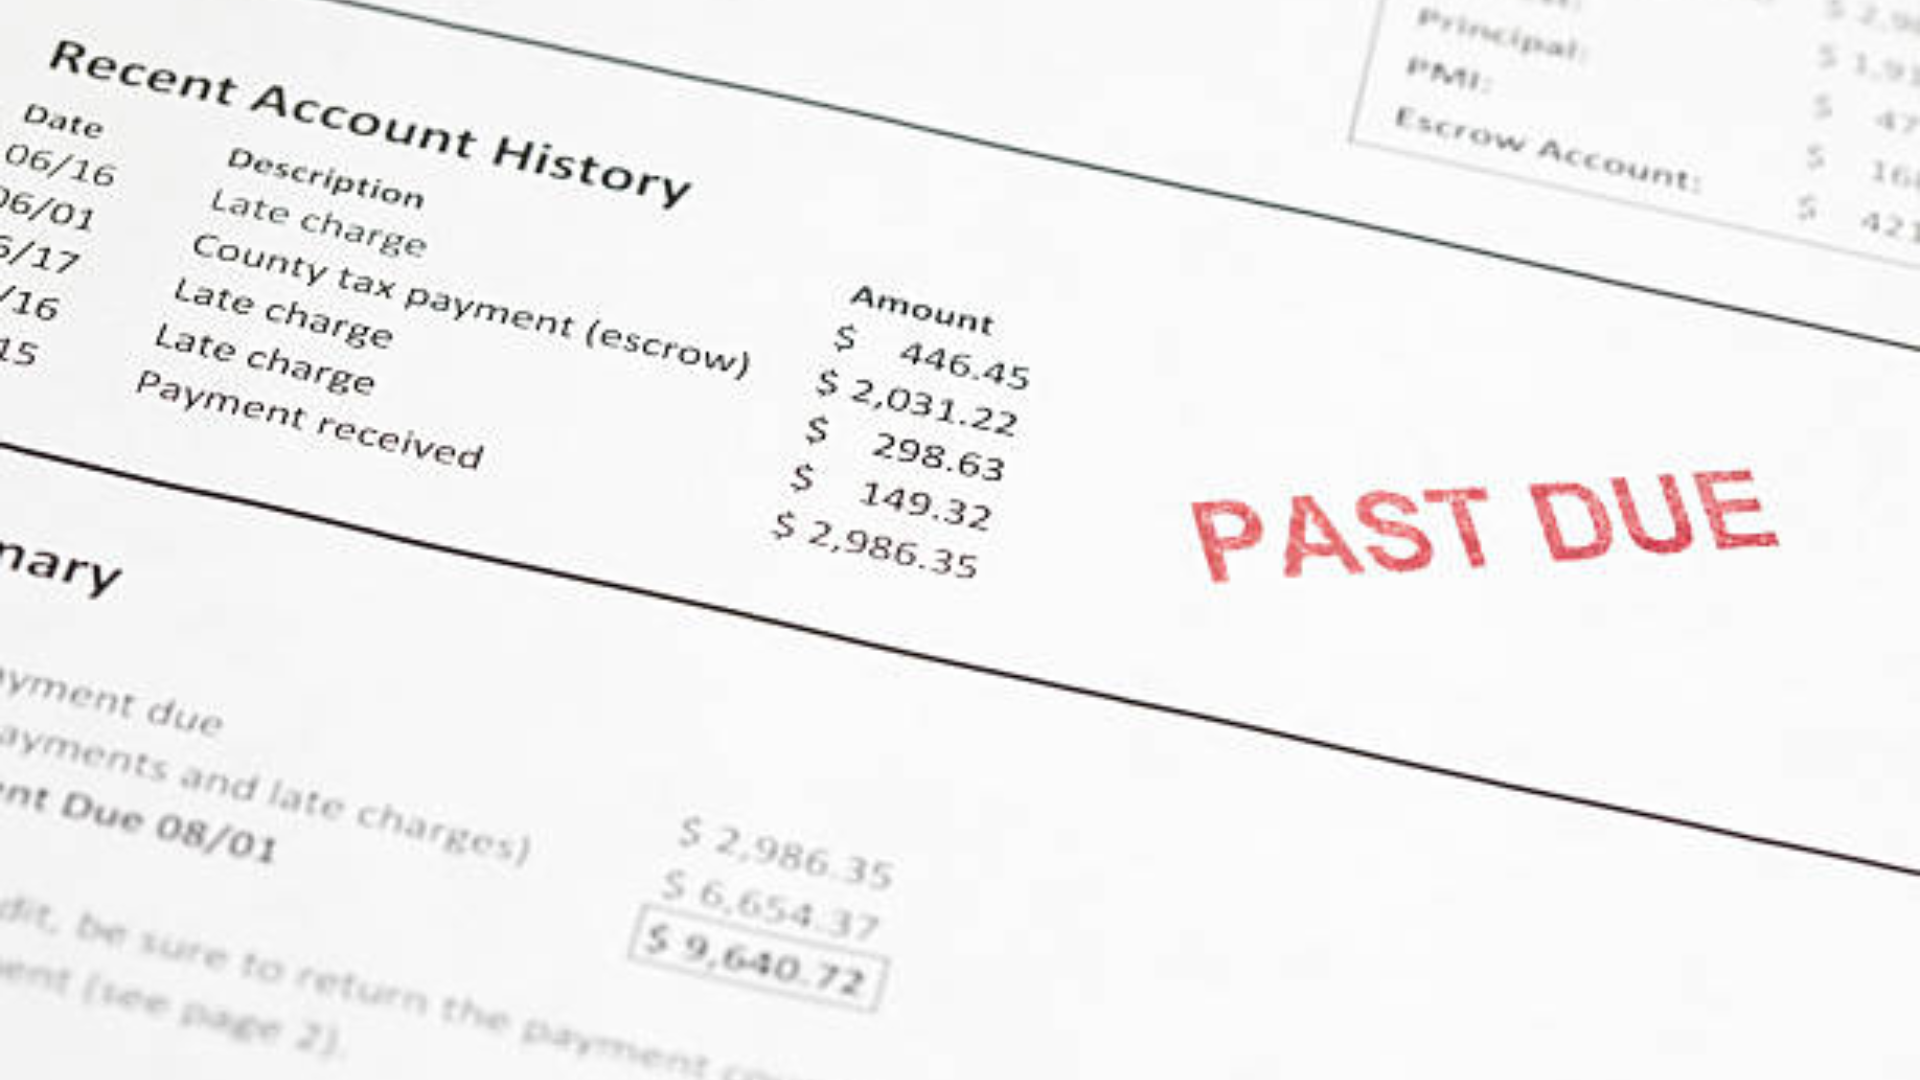
past due accounts in a credit report

Collections and Other Negative Information

If certain unpaid debts are sent to a collection agency, a collection account may appear on your credit report.


Other negative information can potentially include serious delinquencies, repossessions, foreclosures, or bankruptcies, depending on the circumstances.


The length of time negative information remains on a credit report varies by type. Even if an account is eventually paid, the previous history may remain visible for a period of time.


This is why addressing financial problems early can be important.
an American holding a paycheck, which isn't included in a credit report

What Does Not Usually Appear?

A credit report is not a complete record of your financial life.


Your income, checking account balance, savings balance, purchases made with cash, and most everyday expenses typically do not appear on a standard credit report.


Your credit report also does not contain your credit score itself in every case. A credit score is calculated separately using information contained in the report.
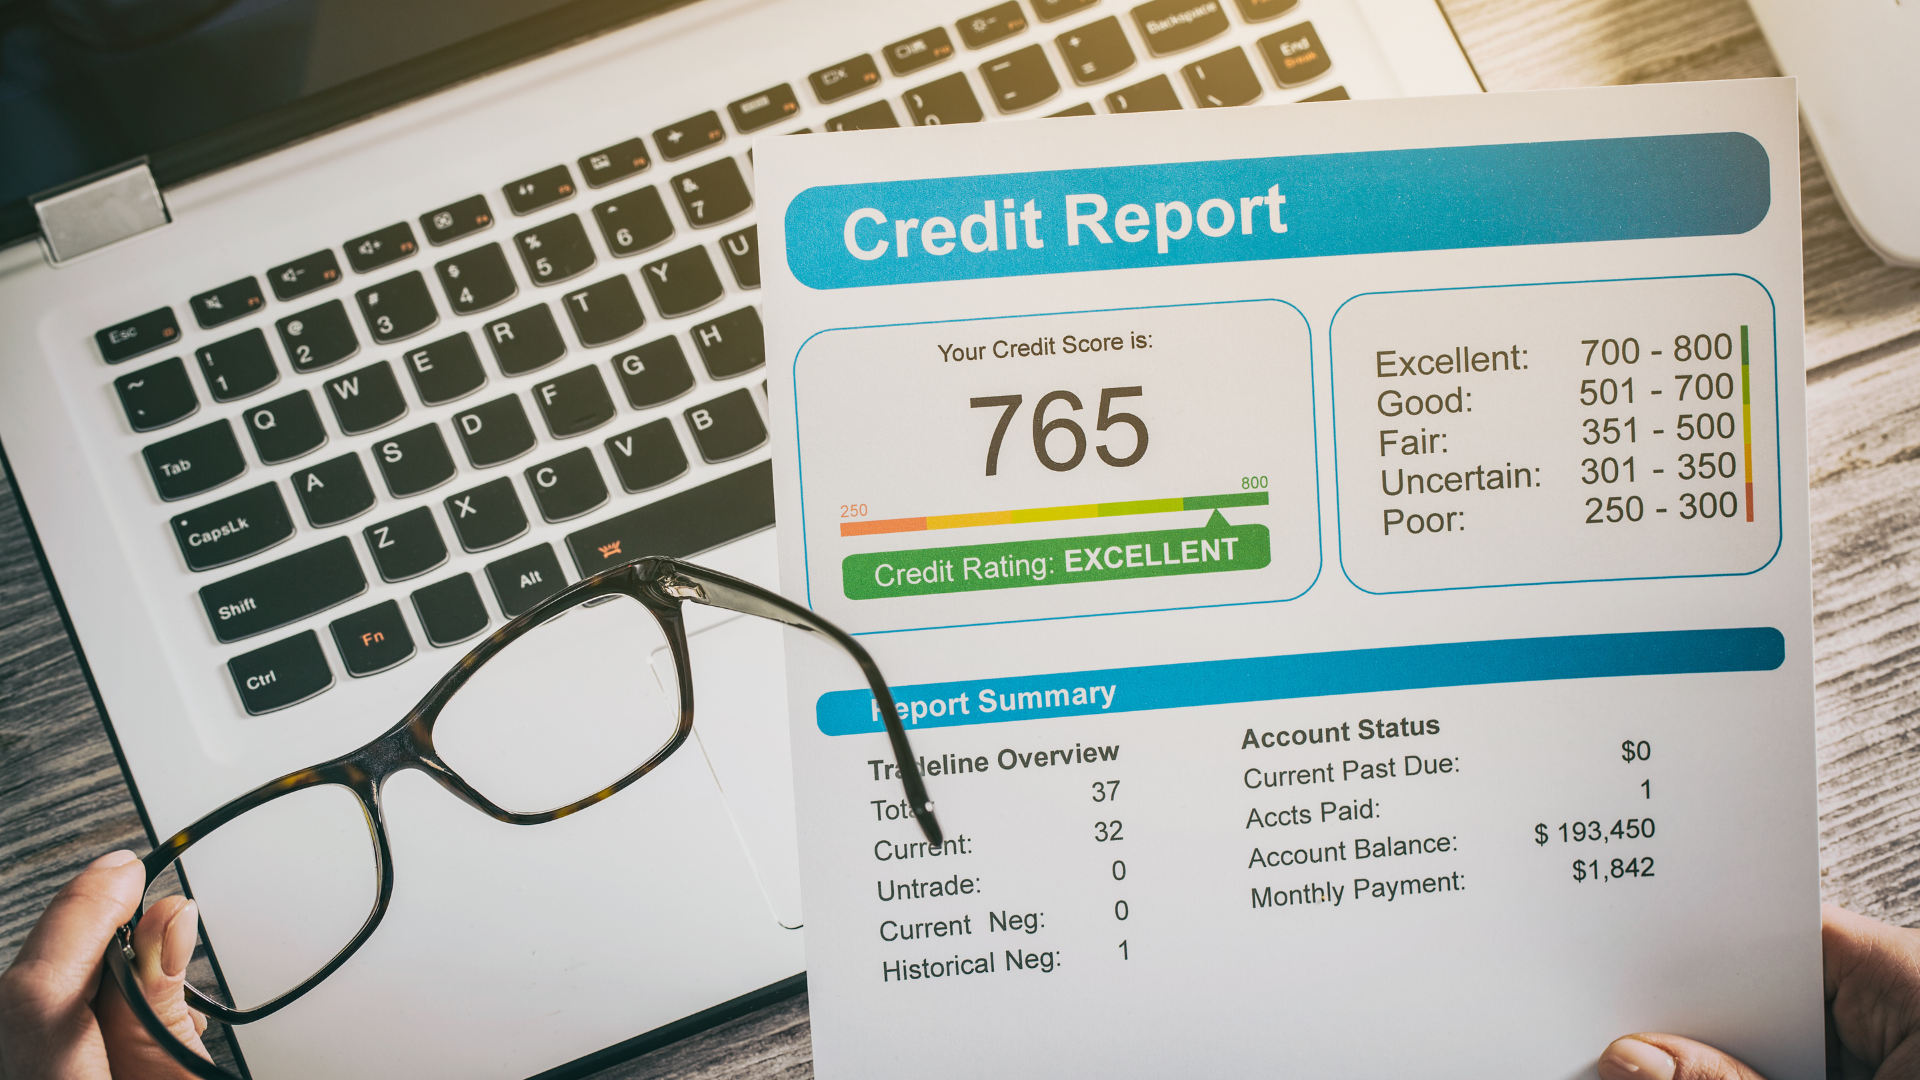
reviewing credit report

Review Your Credit Regularly

Checking your credit report can help you understand how lenders may view your borrowing history and give you an opportunity to catch errors or unfamiliar accounts.


If you find inaccurate information, you can dispute it with the appropriate credit reporting agency. Regular monitoring also makes it easier to see how your payment habits and balances change over time.


Portside Finance supports responsible borrowing and financial education by helping consumers better understand budgeting, credit, and short-term financing. Building strong financial habits begins with knowing where you stand, and reviewing your credit report is one practical way to stay informed.
November 18, 2026
The holiday season can make it easy to spend more than planned . Gifts, travel, meals, decorations, events, and last-minute purchases can all pile up quickly, especially when each expense feels small on its own. The problem often shows up later, when January arrives with credit card balances, regular monthly bills, and less cash available than expected. A holiday budget can help prevent that. The goal is not to remove the fun from the season. It is to decide in advance what you can comfortably spend without creating a financial problem after the holidays are over. Start With One Total Number Before making a gift list, choose the total amount you can realistically afford for the entire holiday season. That number should include more than gifts. Think about travel, food, hosting, decorations, charitable giving, school events, parties, shipping, and anything else that tends to appear between Thanksgiving and New Year’s. Once the total is clear, break it into categories. For example, you may decide how much goes toward gifts, how much toward travel, and how much toward food and entertainment. That makes it easier to see where one category may be taking too much of the overall budget.
November 10, 2026
Some expenses are not true emergencies . They just do not happen every month. Car registration, annual insurance premiums, holiday spending, school costs, home maintenance, vet bills, and seasonal expenses can all feel sudden if there is no money set aside for them. That is where sinking funds can help. A sinking fund is money saved gradually for a specific future expense .  Instead of waiting for the bill to arrive and hoping there is enough room in the budget, you prepare for it a little at a time.
November 4, 2026
Paying off several debts at once can feel discouraging. You may be making payments every month and still feel like none of the balances are moving very fast. Two common payoff strategies can help create more structure: the debt snowball and the debt avalanche . Both methods focus extra money on one debt at a time while maintaining required payments on the others. The difference is which debt you attack first.
October 30, 2026
Car repairs have a way of arriving at the worst possible time. Sometimes the mechanic gives you a list of problems instead of one simple fix. Maybe the brakes need attention, the tires are worn, a warning light is on, and another repair is recommended soon. If your budget cannot cover everything at once, the situation can feel overwhelming. The goal is not to ignore the problems. It is to rank them carefully so the most important repairs are handled first.
October 22, 2026
Some months are simply more expensive than others.  A car repair, annual insurance premium , medical bill, school expense, utility spike, or home maintenance cost can all land within the same few weeks. When that happens, even a normally workable budget can feel stretched. The goal is not to pretend every bill can be handled comfortably. It is to slow down, organize the situation, and decide what needs attention first.
October 14, 2026
A budget is not supposed to be permanent.  It is a working plan for the money you have right now. When your income changes, that plan should change with it. A raise, reduced work hours, a new job, overtime, seasonal income, or a temporary gap between paychecks can all change what is realistic. If the budget stays the same while income moves up or down, financial stress can build quickly. Updating the budget helps keep spending, saving, and debt payments aligned with what is actually coming in.
October 9, 2026
It can be confusing to check your credit score in one place, then see a different number somewhere else. One app may show a score of 690, while a lender pulls a score that is noticeably higher or lower. That does not necessarily mean one of them is wrong. Consumers can have multiple valid credit scores at the same time because different scoring models, credit bureaus, and reporting dates may be used. Understanding why those differences happen can make credit monitoring less frustrating.
September 29, 2026
When comparing loan offers, the monthly payment is often the first number people look at. That makes sense because the payment has to fit into the household budget. But a lower monthly payment does not always mean a lower-cost loan. In many cases, the payment is smaller because the repayment period is longer. That may make the loan easier to manage from month to month, but it can also increase the total amount paid over time. Understanding the difference between monthly affordability and total borrowing cost can help consumers make more informed decisions.
September 23, 2026
Closing an old credit card can feel like a smart financial move, especially if you no longer use the account or want to simplify your finances. But before you close it, it helps to understand how that decision may affect your overall credit profile . Credit scores are influenced by several factors, including payment history, credit utilization, account age, and the mix of credit you have. Closing an older card can affect more than one of those areas, depending on your balances and the rest of your accounts.
September 16, 2026
When comparing loans, the monthly payment often gets the most attention. It is easy to understand why: borrowers need to know whether the payment fits into the budget. But the monthly payment does not tell the whole story.  Another number to review is the annual percentage rate , or APR. APR can help borrowers compare the cost of different loans by expressing certain borrowing costs as a yearly percentage. Understanding what that number represents can make it easier to evaluate whether one loan is more expensive than another.
More Posts