Why Cash Flow Stability Matters More Than Many People Realize
When people think about financial health, they often focus primarily on income level, savings balances, or credit scores. While those factors are important, one of the most overlooked aspects of financial stability is cash flow. Even households with steady income can experience financial pressure when the timing of expenses and available funds becomes difficult to manage.
At Portside Finance, we believe understanding cash flow is an important part of building long-term financial stability. In many situations, maintaining predictable monthly cash flow matters just as much as total income alone.
What Is Cash Flow?
Cash flow refers to how money moves in and out of a household over time. Positive cash flow generally means income is arriving consistently enough to cover regular expenses, while negative cash flow occurs when expenses temporarily exceed available funds.
Many financial challenges are connected not necessarily to a lack of income, but to interruptions or imbalances in timing between bills, emergencies, and available cash.
Examples may include:
- Unexpected vehicle repairs
- Medical expenses
- Seasonal utility increases
- Reduced work hours
- Emergency travel costs
- Temporary household disruptions
Even financially responsible individuals may experience short-term cash flow strain when several expenses occur at once.
Stable Cash Flow Reduces Financial Stress
One reason cash flow matters so much is because predictability helps reduce uncertainty. When households can reliably manage monthly obligations without constantly shifting funds between expenses, overall financial stress often becomes more manageable.
Cash flow instability, on the other hand, may create ongoing pressure surrounding:
- Bill payment timing
- Account balances
- Emergency preparedness
- Daily budgeting decisions
- Unexpected expenses
Over time, this uncertainty can make financial planning feel overwhelming even for households with otherwise stable income.
Income Alone Does Not Guarantee Stability
Many people assume that higher income automatically prevents financial stress. In reality, cash flow problems can affect households across a wide range of income levels.
Larger incomes are often accompanied by larger financial obligations, including mortgages, vehicle payments, insurance costs, childcare expenses, and other recurring responsibilities.
A temporary interruption or unexpected expense may still create cash flow strain regardless of overall income level if monthly obligations remain high.
This is one reason budgeting and financial structure remain important at every income level.
Irregular Expenses Create Common Challenges
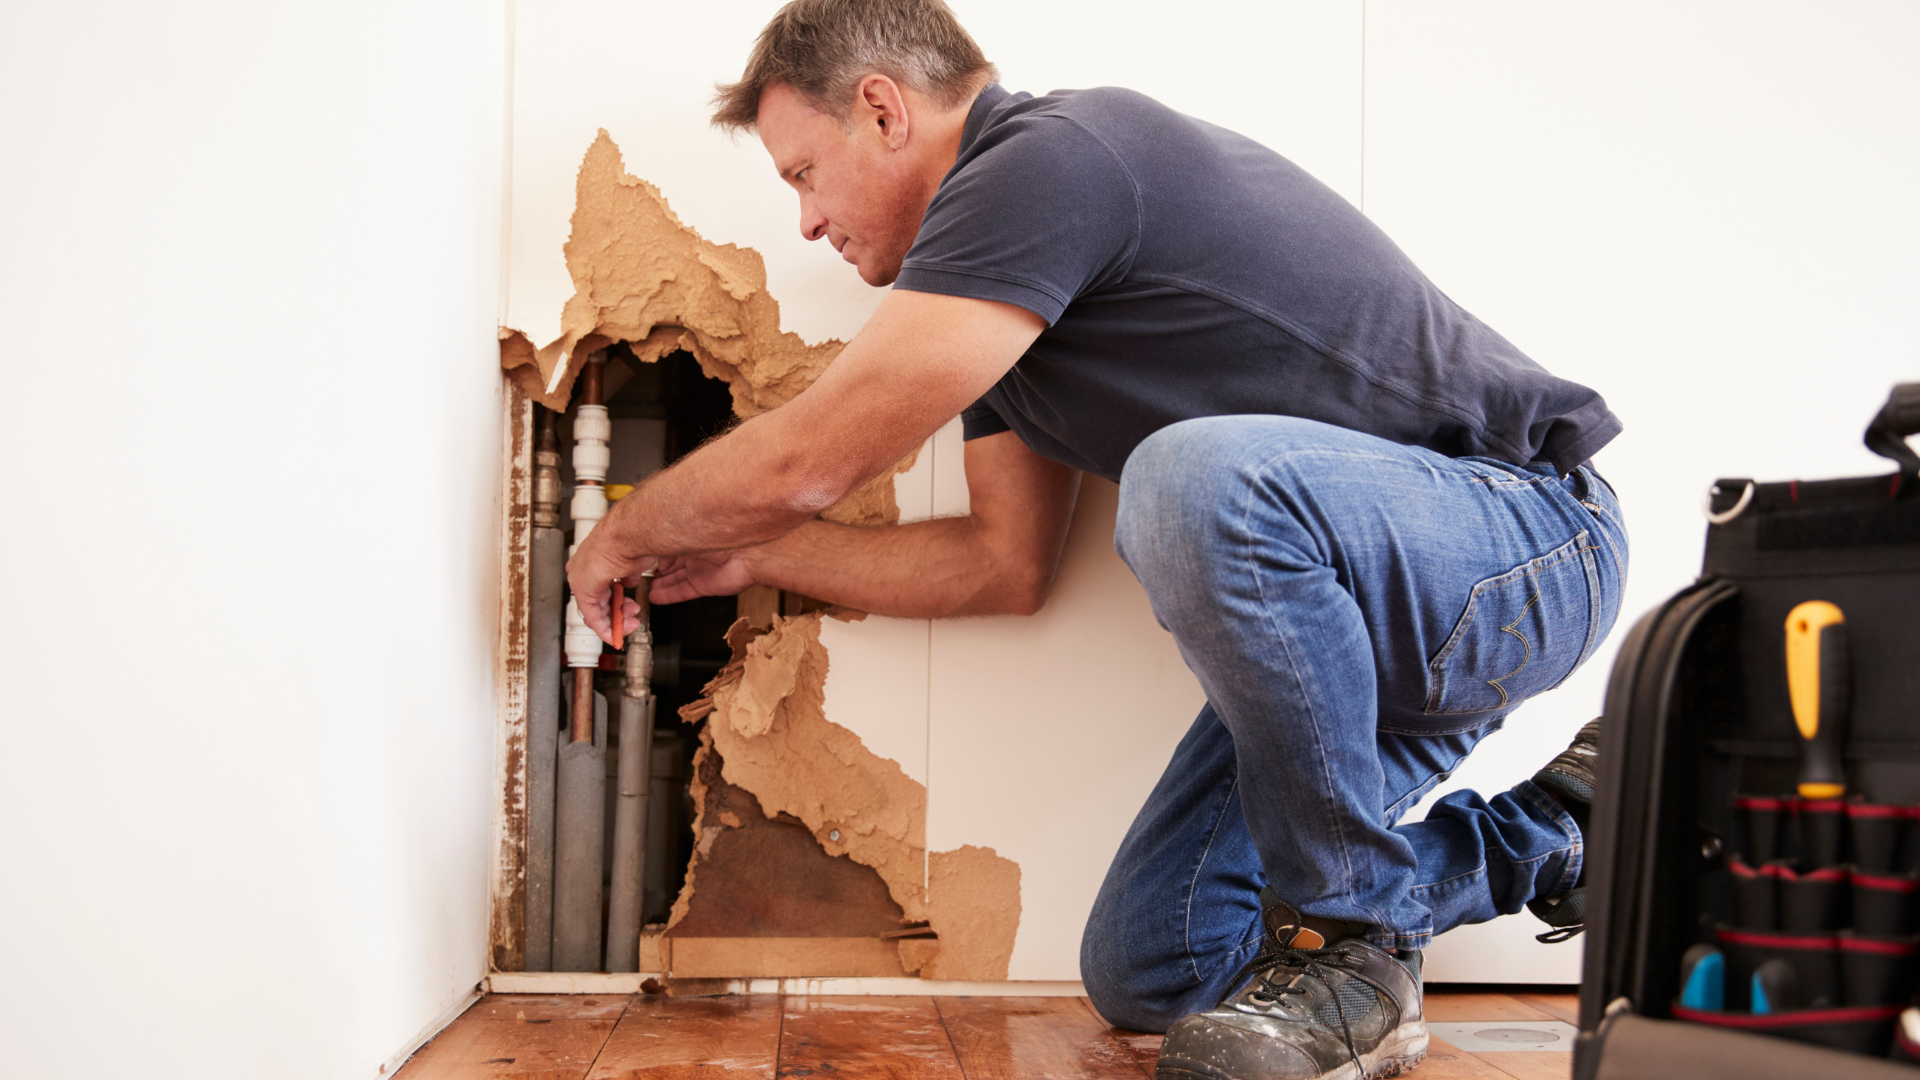
One of the biggest threats to stable cash flow is irregular expenses. Monthly bills are often predictable, but many real-world expenses are not.
For example:
- Vehicle breakdowns
- Home repairs
- Medical costs
- School expenses
- Seasonal travel
- Emergency purchases
can all disrupt carefully planned budgets.
Without flexibility built into the financial plan, these expenses may create temporary gaps that become difficult to manage comfortably.
Predictability Improves Financial Decision-Making
Stable cash flow also supports better long-term decision-making. When individuals are not operating under constant financial pressure, it often becomes easier to budget responsibly, plan ahead, and evaluate expenses more carefully.
Financial instability frequently increases emotional decision-making because urgent needs create immediate stress. Predictable cash flow helps reduce that pressure and creates greater flexibility for managing everyday obligations.
Even small improvements in monthly financial organization can contribute to greater overall stability.
Responsible Borrowing Can Support Cash Flow Management
In some situations, structured borrowing tools may help households manage temporary financial gaps more predictably. Responsible installment loans, for example, may allow individuals to spread larger expenses into manageable payments rather than absorbing the full cost immediately.
The key is approaching borrowing as a structured financial tool rather than impulsive spending.
At Portside Finance, we encourage borrowers to focus on repayment planning, budgeting awareness, and responsible borrowing practices that support long-term financial organization.
Financial Stability Often Depends on Consistency
Many people think financial wellness is built entirely around large savings goals or major investments. In reality, day-to-day consistency often plays an equally important role.
Stable cash flow helps households:
- Manage bills more comfortably
- Reduce financial stress
- Handle unexpected expenses more effectively
- Improve budgeting predictability
- Maintain greater overall financial control
Over time, these small improvements contribute to stronger financial confidence and healthier financial habits.
Supporting Better Financial Stability
Cash flow stability affects far more than monthly budgeting alone. It influences stress levels, decision-making, financial flexibility, and overall confidence in managing daily life.
At Portside Finance, we provide financial solutions designed to help individuals navigate temporary financial challenges responsibly while supporting healthier long-term financial management. Whether facing an unexpected expense or seeking greater budgeting flexibility, understanding and protecting cash flow is an important part of maintaining overall financial stability.