What Lenders Look for Beyond Your Credit Score

January 21, 2026

When people think about applying for a loan, credit score is often the first thing that comes to mind. While credit scores are important, they are only one part of the picture. In reality, lenders evaluate a range of factors to understand a borrower’s overall financial situation and ability to repay a loan responsibly. Knowing what lenders look for beyond a credit score can help borrowers prepare and make more confident financial decisions.
Income Stability Matters

One of the most important considerations for lenders is income stability. Consistent income demonstrates the ability to make regular payments over time. This does not necessarily mean income must come from a single employer or remain unchanged for years, but lenders often look for reliability and predictability.


Regular paychecks, steady self-employment income, or consistent benefits can all support a borrower’s application. Gaps in income may raise questions, but they do not automatically disqualify someone. Context and explanation often matter.
Payment History Tells a Story

Beyond the numerical score itself, lenders review patterns in payment history. This includes whether bills and obligations are paid on time and how past financial challenges were handled.


A missed payment years ago does not define a borrower. What matters more is whether there is a recent pattern of responsibility. Lenders look for evidence that a borrower understands their obligations and takes them seriously.
Debt to Income Ratio

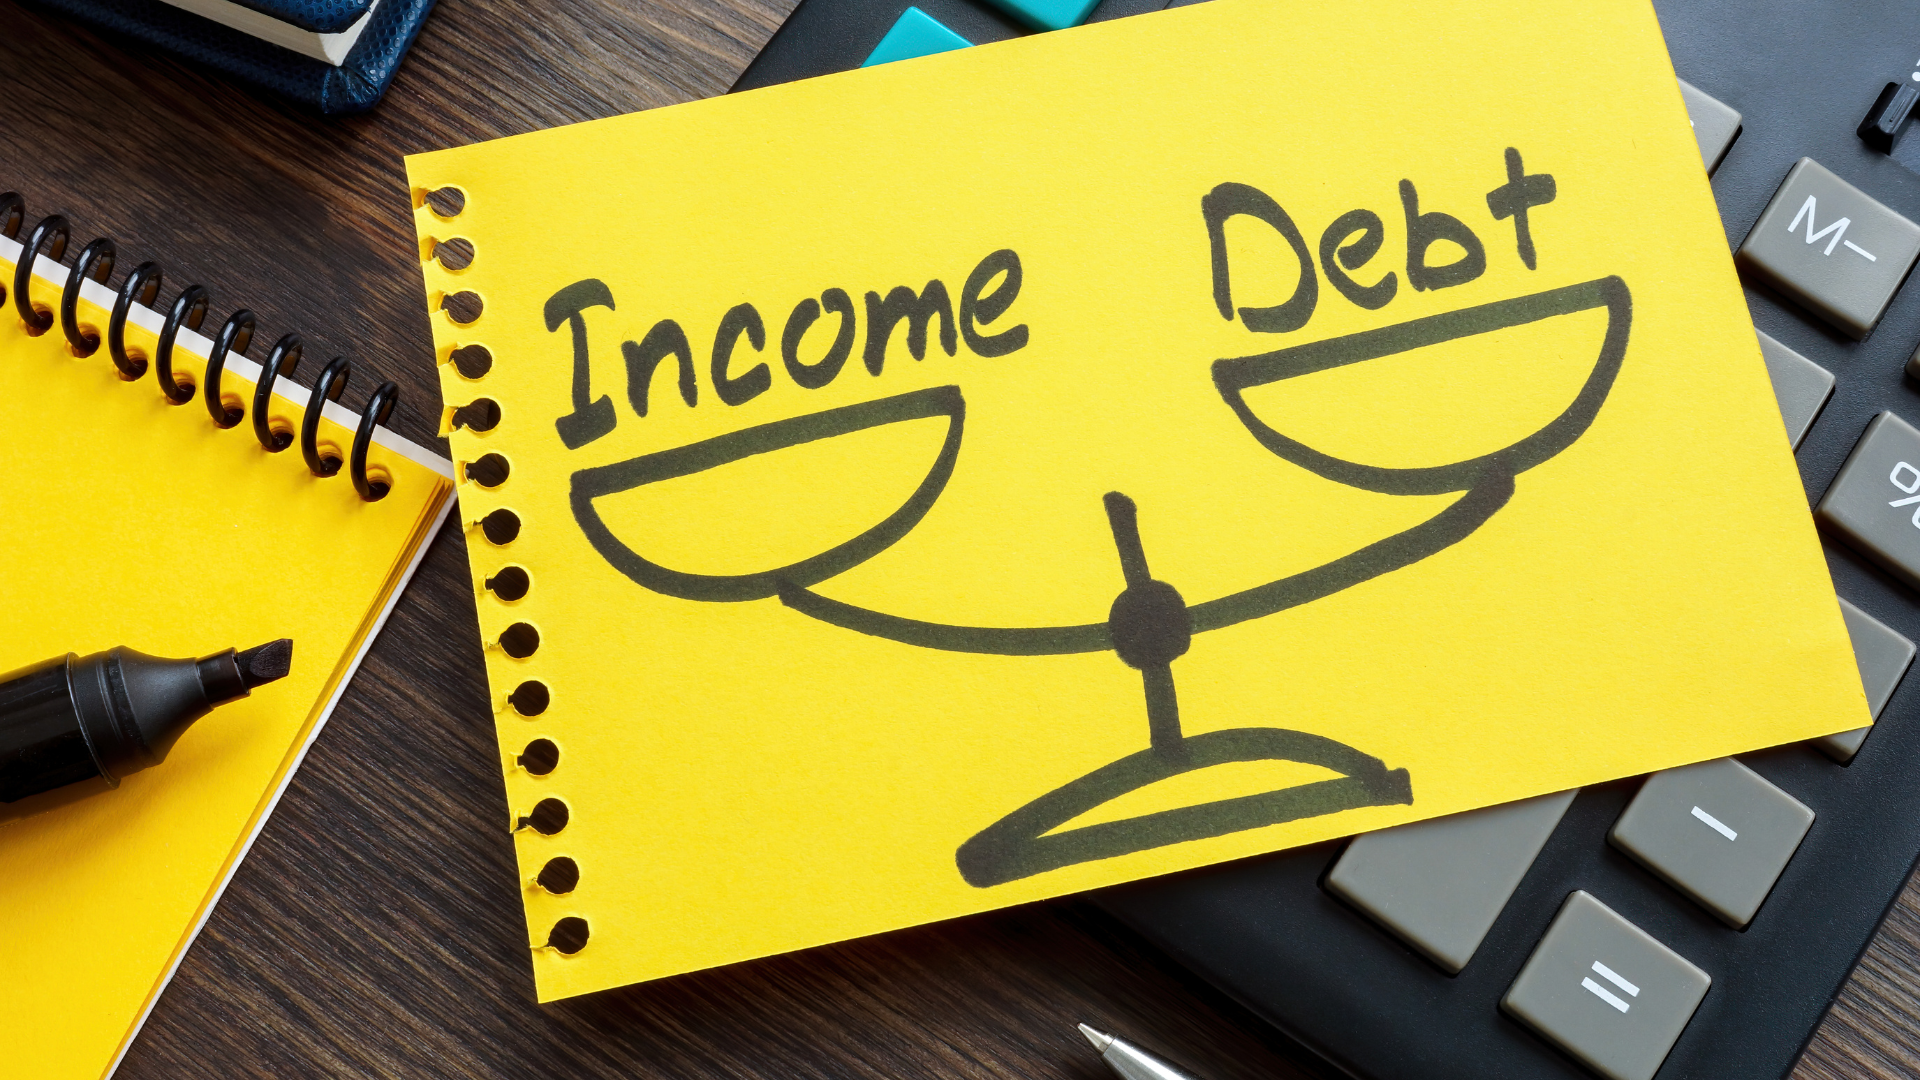
Another key factor is debt to income ratio. This measures how much of a borrower’s monthly income is already committed to existing obligations. Even with a strong credit score, taking on additional debt may not be advisable if monthly obligations are already high.


A manageable debt to income ratio suggests that a borrower has room in their budget to take on and repay a loan without unnecessary strain.
Cash Flow Awareness

Lenders often evaluate how borrowers manage cash flow. This includes whether income aligns with expenses and whether there is a pattern of budgeting and planning.


Borrowers who understand their monthly expenses and can articulate how a loan fits into their financial picture tend to be better positioned for success. Clear planning shows intention rather than impulse.
Employment and Residency Consistency

Consistency in employment and residence can also factor into lending decisions. Frequent changes are not inherently negative, but stability often provides reassurance that a borrower has a predictable routine and support system.


This information helps lenders understand overall reliability and reduces uncertainty.
Loan Purpose and Intent

The reason for borrowing matters. Lenders look more favorably on loans that serve a clear, constructive purpose, such as bridging a temporary gap, consolidating obligations, or managing a planned expense.


Borrowers who can explain how a loan supports their financial goalsdemonstrate responsibility and foresight.
Communication and Transparency

Honest communication plays a meaningful role in lending decisions. Providing accurate information, responding promptly to requests, and asking questions all reflect engagement and seriousness.


Borrowers who approach the process with transparency help lenders make informed decisions and build trust.
Credit Score Is a Tool, Not the Whole Picture

A credit score provides a snapshot, but it does not capture everything. Life events, temporary setbacks, and changing circumstances all affect financial history. Lenders who take a broader view recognize that people are more than a number.


Understanding this can help borrowers feel less discouraged and more empowered when exploring options.
Preparing for a Stronger Application

Borrowers can strengthen their position by reviewing income, understanding monthly obligations, and being clear about their goals. Preparation helps ensure that borrowing decisions align with long term financial health.


At Portside Finance, we believe responsible lending begins with understanding the full financial picture. By looking beyond credit scores, we aim to support borrowers with clarity, respect, and realistic solutions that fit their needs and circumstances.
September 29, 2026
When comparing loan offers, the monthly payment is often the first number people look at. That makes sense because the payment has to fit into the household budget. But a lower monthly payment does not always mean a lower-cost loan. In many cases, the payment is smaller because the repayment period is longer. That may make the loan easier to manage from month to month, but it can also increase the total amount paid over time. Understanding the difference between monthly affordability and total borrowing cost can help consumers make more informed decisions.
September 23, 2026
Closing an old credit card can feel like a smart financial move, especially if you no longer use the account or want to simplify your finances. But before you close it, it helps to understand how that decision may affect your overall credit profile . Credit scores are influenced by several factors, including payment history, credit utilization, account age, and the mix of credit you have. Closing an older card can affect more than one of those areas, depending on your balances and the rest of your accounts.
September 16, 2026
When comparing loans, the monthly payment often gets the most attention. It is easy to understand why: borrowers need to know whether the payment fits into the budget. But the monthly payment does not tell the whole story.  Another number to review is the annual percentage rate , or APR. APR can help borrowers compare the cost of different loans by expressing certain borrowing costs as a yearly percentage. Understanding what that number represents can make it easier to evaluate whether one loan is more expensive than another.
September 8, 2026
A credit score can move up or down even when every bill has been paid on time. That can be confusing, especially for someone who assumes payment history is the only factor affecting the number.  Payment history is very important, but credit scoring models also consider other information in your credit report. Changes in balances, account activity, new applications, credit limits, and the age of your accounts can all influence your score. Understanding those factors can make credit changes feel less mysterious and help you focus on habits that matter over time.
September 2, 2026
When you have several debts at the same time, deciding where to focus can feel overwhelming. Credit cards, installment loans, medical balances, auto loans, and other obligations may all have different interest rates, minimum payments, and payoff timelines.  There is no single payoff strategy that is right for everyone. The best approach depends on your budget , interest costs, motivation, and need for financial flexibility. What matters most is choosing a method you can maintain consistently.
August 25, 2026
Your credit score is influenced by several factors, and one of the most important is credit utilization. Even people who consistently pay their bills on time can see their credit scores move up or down depending on how much revolving credit they are using.  Understanding credit utilization can make it easier to manage credit cards strategically, avoid unnecessary score fluctuations, and build healthier long-term financial habits.
August 18, 2026
A credit report is a detailed record of how you have managed certain types of credit and debt. Lenders, landlords, insurers, and other organizations may use information from your credit report when making decisions about applications, rates, deposits, or other financial matters.  Understanding what appears on your credit report can make it easier to monitor your financial history, identify errors, and build stronger credit habits. Portside Finance encourages consumers to review their credit information regularly and understand how everyday borrowing and payment decisions may affect their financial profile.
August 11, 2026
Even a carefully planned budget can get off track. An unexpected car repair, a higher utility bill, a family obligation, or simply a month with more discretionary spending than usual can push expenses beyond the amount originally planned. Going over budget does not mean the entire financial plan has failed. What matters most is how quickly the situation is reviewed and adjusted.  Recovering from an over-budget month starts with understanding what happened, identifying which expenses can be changed, and creating a practical plan for the weeks ahead. Portside Finance encourages consumers to approach short-term financial setbacks with organization, realistic expectations, and responsible decision-making rather than panic.
August 4, 2026
Strong money management is not about earning a certain income or having extensive financial experience. It is about developing habits that help you make informed decisions, prepare for unexpected expenses, and work toward your financial goals with confidence. Whether you are just beginning your financial journey or looking to strengthen your current routine, improving your money management skills can provide long-term benefits.  Every financial situation is unique, but a few practical strategies can help almost anyone build a stronger financial foundation. Portside Finance encourages responsible financial planning and believes that informed decisions today can support greater financial stability tomorrow.
July 28, 2026
Unexpected expenses are a part of life. A vehicle may require an expensive repair, a home appliance may stop working without warning, or an unforeseen medical expense could suddenly affect your monthly budget. While it is impossible to predict when these situations will arise, preparing for them financially can help reduce stress and make it easier to move forward with confidence.  One of the most effective ways to prepare for life’s surprises is by building an emergency fund . Even modest savings set aside over time can provide valuable financial flexibility when unexpected costs occur.
More Posts