Credit Scores and Loan Approval: What Borrowers Should Know

September 17, 2025

When applying for a loan, one of the first factors lenders consider is your credit score. This number reflects your history of managing debt and plays a major role in determining whether you qualify for financing, what interest rate you are offered, and the overall terms of your loan. At Portside Finance, we believe in educating borrowers so they can approach the lending process with confidence. Understanding how credit scores work and how they affect loan approval is the first step toward making informed financial decisions.
What Is a Credit Score?

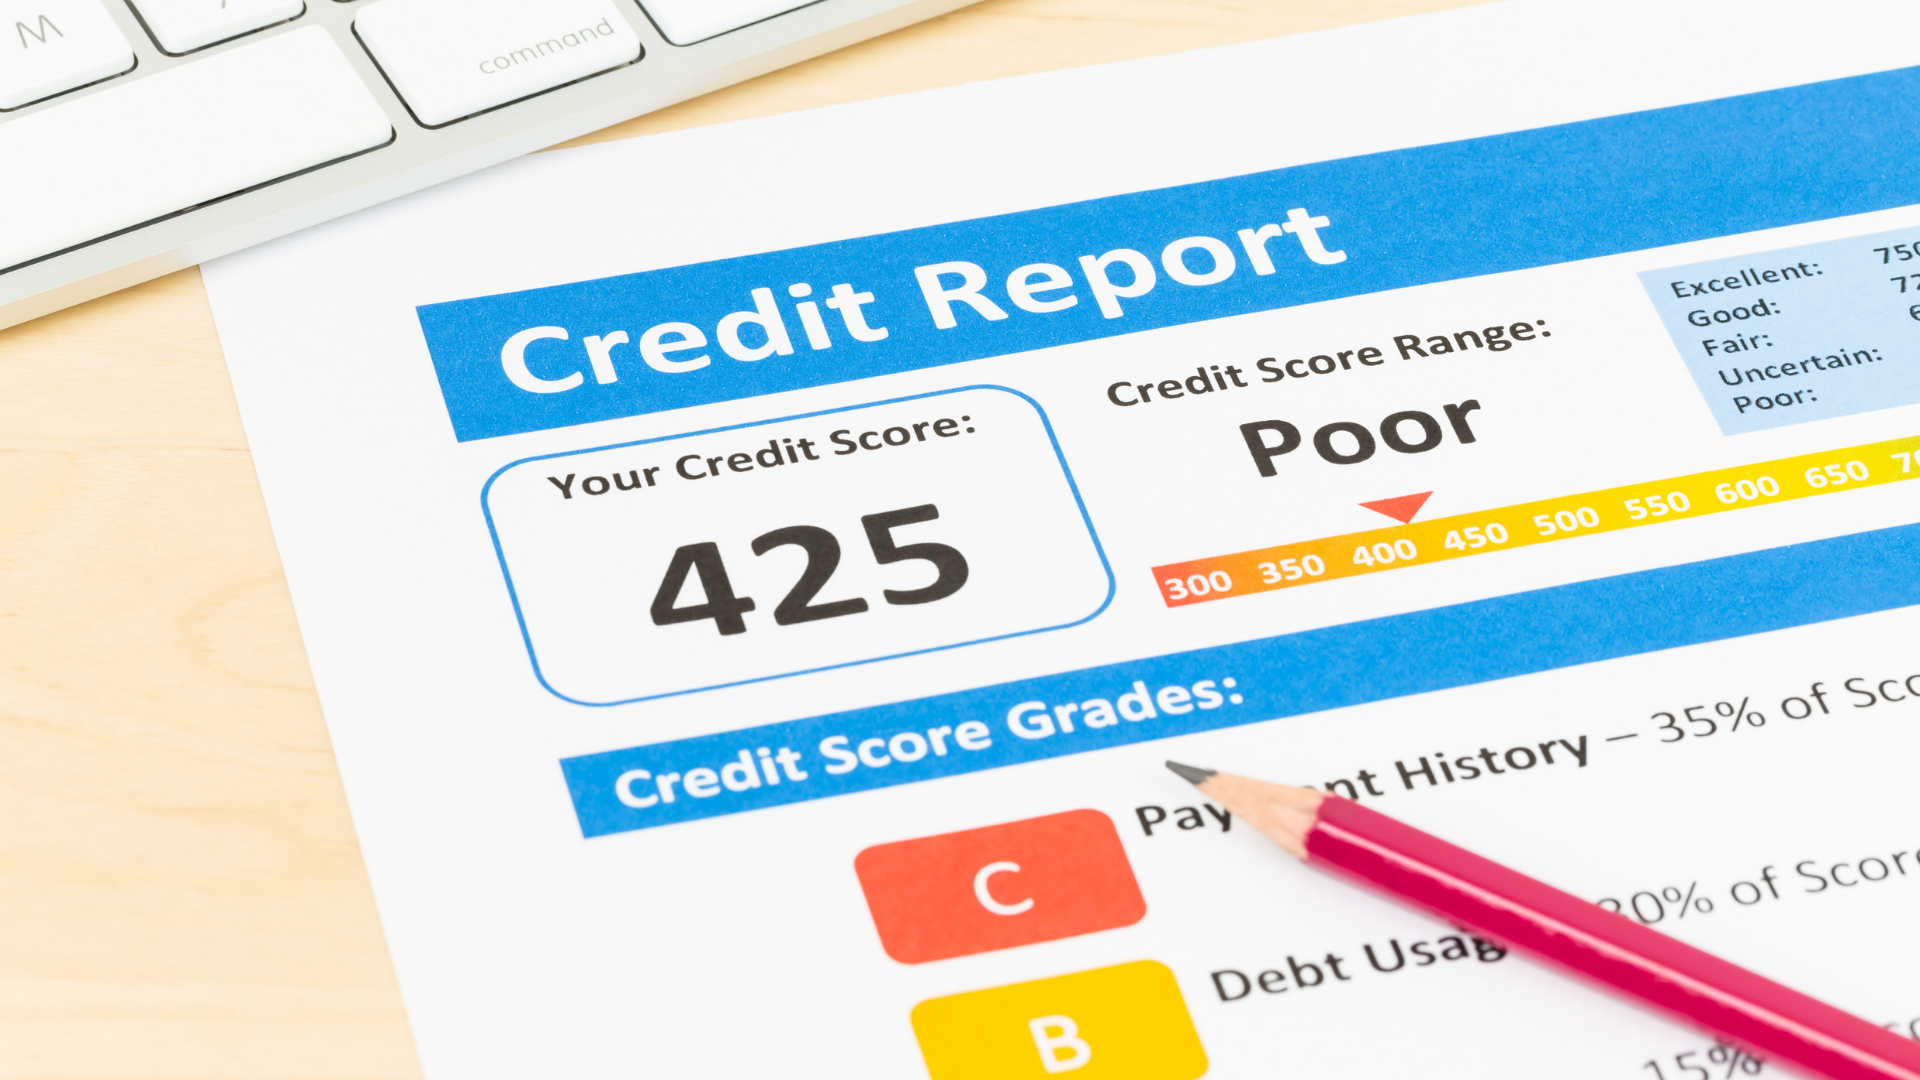
A credit score is a three-digit number, usually between 300 and 850, that summarizes your credit history. It is calculated based on information in your credit report, including payment history, credit utilization, length of credit history, types of accounts, and recent credit inquiries.


  • Payment history shows whether you have paid bills on time.
  • Credit utilization reflects the percentage of available credit you are using.
  • Length of history measures how long you have maintained accounts.
  • Credit mix accounts for different types of loans, such as credit cards, auto loans, or mortgages.
  • Inquiries track how often you apply for new credit.


Together, these factors provide lenders with a snapshot of your financial reliability.
Why Credit Scores Matter

Lenders use credit scores to assess risk. A higher score suggests that a borrower is more likely to repay on time, which often results in better loan terms. Conversely, lower scores may lead to higher interest rates or limited approval. While credit scores are important, they are not the only factor lenders consider. Income, employment stability, and the type of loan requested also influence decisions.


What Scores Mean for Borrowers

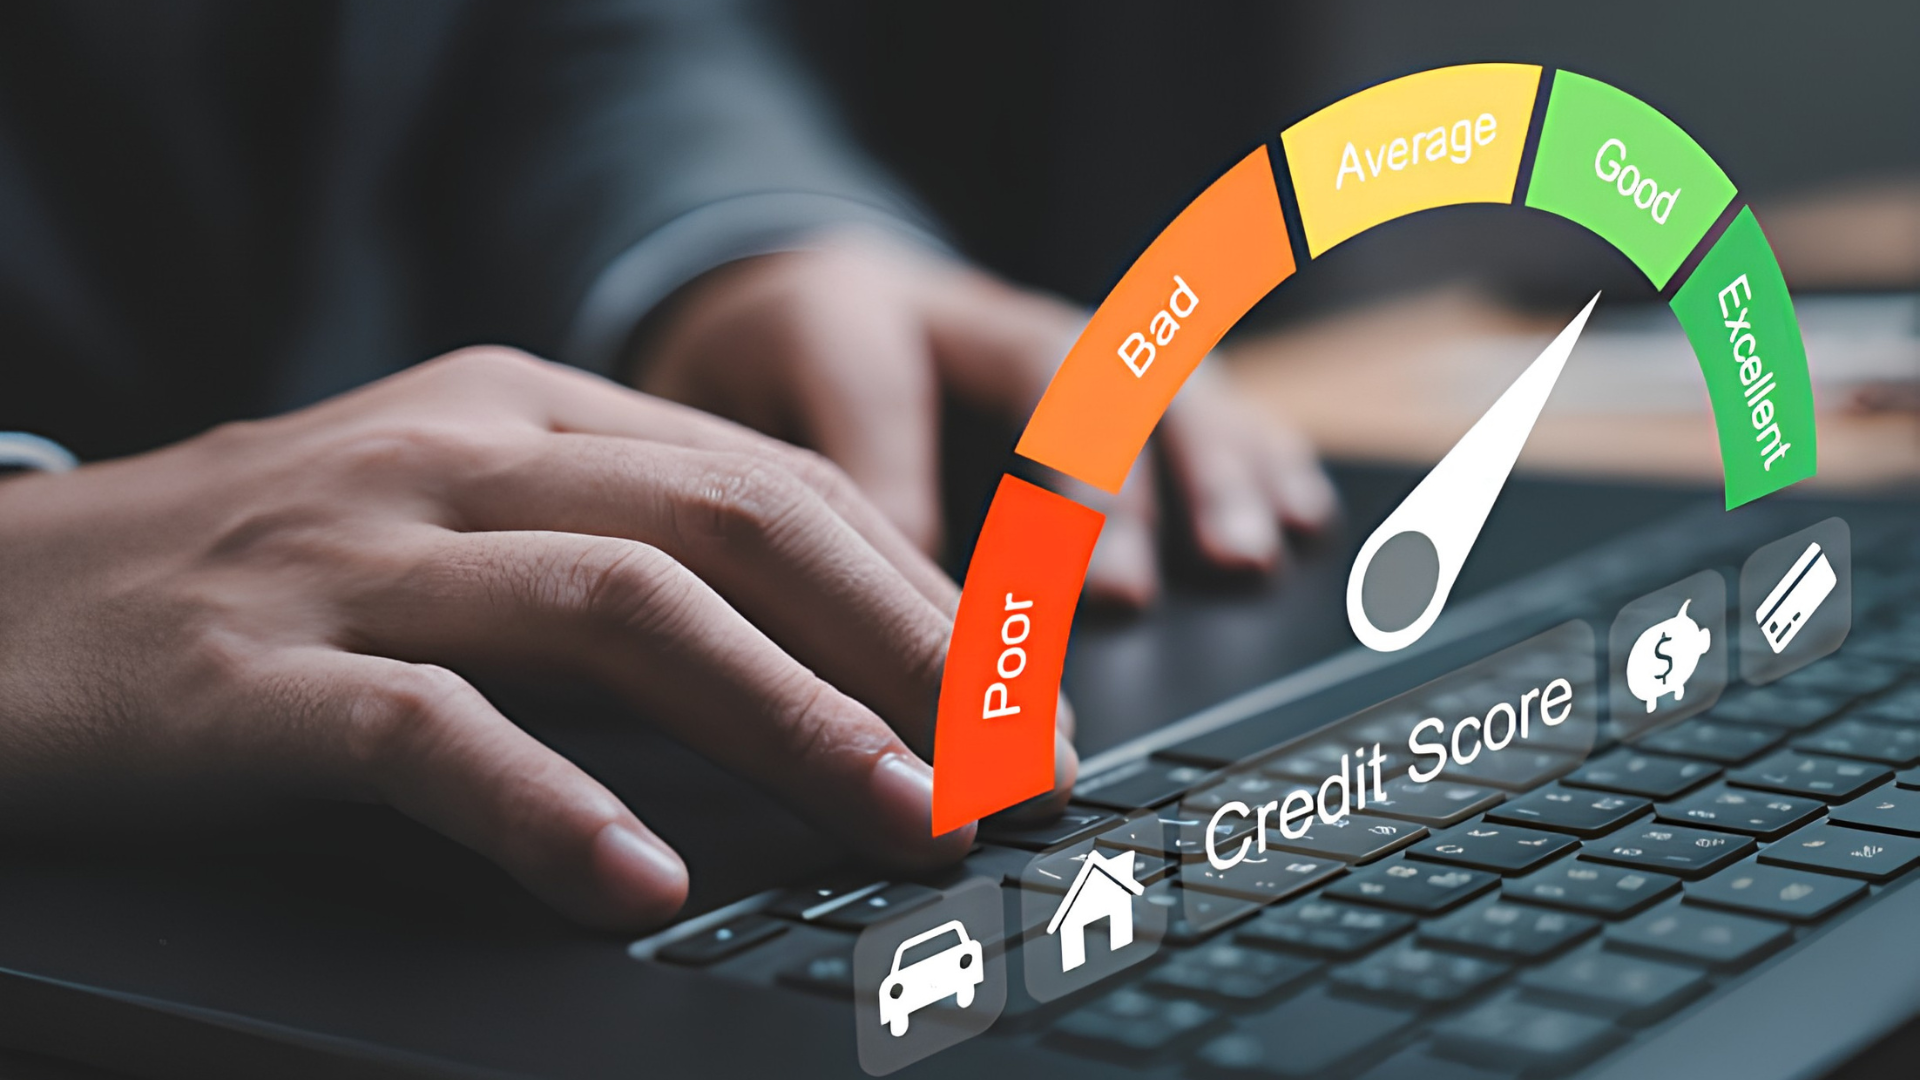
In general, borrowers with scores above 700 are considered to have good credit, while those above 750 are considered excellent. These borrowers typically qualify for lower interest rates and more flexible terms. Scores between 600 and 699 may still secure approval but may come with higher costs. Borrowers with scores below 600 often face challenges but may still qualify for certain secured loans, where collateral reduces risk for the lender.


At Portside Finance, we work with borrowers across the credit spectrum. We recognize that a single number does not tell the whole story, and we focus on finding solutions that meet individual needs.
Secured Loans and Credit Scores

One way to improve approval chances is by applying for a secured loan, such as an auto title loan. Because collateral reduces risk, lenders may be more willing to approve loans for borrowers with less-than-perfect credit. Secured loans can provide a path toward rebuilding credit when used responsibly, since consistent payments help improve credit history over time.


How to Improve Your Credit Score

Improving a credit score takes time, but even small changes can have a significant impact:


  • Pay all bills on time, since payment history has the greatest weight.
  • Reduce credit card balances to lower utilization.
  • Avoid applying for multiple loans or credit cards at once.
  • Keep older accounts open to demonstrate a long history of responsible credit use.

By practicing good credit habits, borrowers not only increase their chances of approval but also secure better loan terms in the future.
Final Thoughts

Credit scores are an important factor in the lending process, but they do not define your financial future. With the right information and responsible borrowing practices, it is possible to improve your score and gain access to better opportunities.


At Portside Finance, we believe every borrower deserves fair and transparent options. Whether your credit is strong or needs improvement, our team works with you to find lending solutions that meet your needs and set you on a path toward greater financial confidence.
October 9, 2026
It can be confusing to check your credit score in one place, then see a different number somewhere else. One app may show a score of 690, while a lender pulls a score that is noticeably higher or lower. That does not necessarily mean one of them is wrong. Consumers can have multiple valid credit scores at the same time because different scoring models, credit bureaus, and reporting dates may be used. Understanding why those differences happen can make credit monitoring less frustrating.
September 29, 2026
When comparing loan offers, the monthly payment is often the first number people look at. That makes sense because the payment has to fit into the household budget. But a lower monthly payment does not always mean a lower-cost loan. In many cases, the payment is smaller because the repayment period is longer. That may make the loan easier to manage from month to month, but it can also increase the total amount paid over time. Understanding the difference between monthly affordability and total borrowing cost can help consumers make more informed decisions.
September 23, 2026
Closing an old credit card can feel like a smart financial move, especially if you no longer use the account or want to simplify your finances. But before you close it, it helps to understand how that decision may affect your overall credit profile . Credit scores are influenced by several factors, including payment history, credit utilization, account age, and the mix of credit you have. Closing an older card can affect more than one of those areas, depending on your balances and the rest of your accounts.
September 16, 2026
When comparing loans, the monthly payment often gets the most attention. It is easy to understand why: borrowers need to know whether the payment fits into the budget. But the monthly payment does not tell the whole story.  Another number to review is the annual percentage rate , or APR. APR can help borrowers compare the cost of different loans by expressing certain borrowing costs as a yearly percentage. Understanding what that number represents can make it easier to evaluate whether one loan is more expensive than another.
September 8, 2026
A credit score can move up or down even when every bill has been paid on time. That can be confusing, especially for someone who assumes payment history is the only factor affecting the number.  Payment history is very important, but credit scoring models also consider other information in your credit report. Changes in balances, account activity, new applications, credit limits, and the age of your accounts can all influence your score. Understanding those factors can make credit changes feel less mysterious and help you focus on habits that matter over time.
September 2, 2026
When you have several debts at the same time, deciding where to focus can feel overwhelming. Credit cards, installment loans, medical balances, auto loans, and other obligations may all have different interest rates, minimum payments, and payoff timelines.  There is no single payoff strategy that is right for everyone. The best approach depends on your budget , interest costs, motivation, and need for financial flexibility. What matters most is choosing a method you can maintain consistently.
August 25, 2026
Your credit score is influenced by several factors, and one of the most important is credit utilization. Even people who consistently pay their bills on time can see their credit scores move up or down depending on how much revolving credit they are using.  Understanding credit utilization can make it easier to manage credit cards strategically, avoid unnecessary score fluctuations, and build healthier long-term financial habits.
August 18, 2026
A credit report is a detailed record of how you have managed certain types of credit and debt. Lenders, landlords, insurers, and other organizations may use information from your credit report when making decisions about applications, rates, deposits, or other financial matters.  Understanding what appears on your credit report can make it easier to monitor your financial history, identify errors, and build stronger credit habits. Portside Finance encourages consumers to review their credit information regularly and understand how everyday borrowing and payment decisions may affect their financial profile.
August 11, 2026
Even a carefully planned budget can get off track. An unexpected car repair, a higher utility bill, a family obligation, or simply a month with more discretionary spending than usual can push expenses beyond the amount originally planned. Going over budget does not mean the entire financial plan has failed. What matters most is how quickly the situation is reviewed and adjusted.  Recovering from an over-budget month starts with understanding what happened, identifying which expenses can be changed, and creating a practical plan for the weeks ahead. Portside Finance encourages consumers to approach short-term financial setbacks with organization, realistic expectations, and responsible decision-making rather than panic.
August 4, 2026
Strong money management is not about earning a certain income or having extensive financial experience. It is about developing habits that help you make informed decisions, prepare for unexpected expenses, and work toward your financial goals with confidence. Whether you are just beginning your financial journey or looking to strengthen your current routine, improving your money management skills can provide long-term benefits.  Every financial situation is unique, but a few practical strategies can help almost anyone build a stronger financial foundation. Portside Finance encourages responsible financial planning and believes that informed decisions today can support greater financial stability tomorrow.
More Posts